Should you rent out your home instead of selling in a stalling market?

Bright MLS just described this fall as "a stalling housing market." Buyers are pulling back, and homes are taking longer to sell.
If you're thinking about selling, that leaves most owners with two choices: cut the price, or wait. There's a third one people don't talk about enough. You can rent the home out instead.
It's a smart move for some owners and a costly one for others. Here's how to tell which one you are.
Why are more owners thinking about renting instead of selling?
Two reasons.
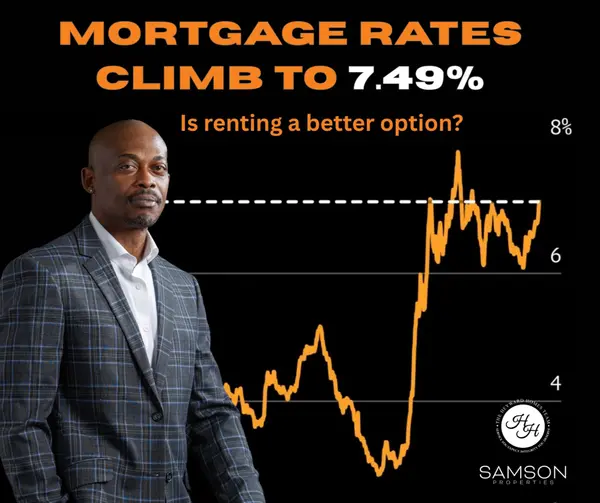
First, a lot of owners have a mortgage rate they'd hate to give up. About half of all U.S. mortgages carry a rate under 4%, according to a Realtor.com analysis of federal data. Today's rates are above 7%. Sell, and that low rate is gone. Rent it out, and you keep it.
Second, owners are sitting on a lot of equity. U.S. mortgage holders have a record $18 trillion in home equity, according to ICE. That gives many owners room to move without selling.
Who is renting out a good fit for?
In my experience, it works best when most of these are true:
- You've owned your home for 5 years or more. Longer ownership usually means more equity and a lower mortgage balance compared with what the home rents for.
- You have real equity, and you don't need all of it for your next home. If you can buy your next place without cashing out this one, renting becomes an option.
- Your debt-to-income ratio is low. You'll need to qualify for your next mortgage while still carrying this one. Lenders look closely at that.
- You have cash set aside. Rentals have empty months and surprise repairs. A cushion keeps one bad month from becoming a crisis.
- You have a mortgage rate worth keeping. The lower your rate, the better renting tends to look.
Who should probably sell instead?
Renting is the wrong move if:
- You need the equity for your next down payment. If the cash is your next home, selling is usually the cleaner path.
- Your finances are stretched. If carrying two homes would push your budget, the risk isn't worth it.
- You bought recently. Many owners who bought in the last few years have little equity. Maryland also has fewer equity-rich homes than most states, with about 28% of mortgaged homes there compared with 41% nationally, according to ATTOM. Check your actual numbers before you assume.
Can you tap your equity and still keep the home as a rental?
Often, yes. Depending on your situation, you may be able to use some of your equity for your next move while keeping this home as a rental.
The timing matters. Equity loans and lines of credit usually come with better terms while you still live in the home than after it becomes a rental. And a signed lease on the rental can sometimes help you qualify for your next mortgage, depending on the loan program.
As a loan officer, this is a conversation I have all the time. The right order of steps can make the difference between a smooth move and a stuck one.
What does it take to be a landlord in Prince George's County?
More than most first-time landlords expect. Prince George's County requires a rental license and an inspection for single-family rentals. Homes built before 1978 have Maryland lead paint rules to follow. Then there's screening tenants, collecting rent, handling repairs and knowing landlord-tenant law.
That's what Heyward Homes Property Management handles. We run credit and background checks on every tenant, collect rent, coordinate repairs and keep you compliant. You also get a monthly statement of income and expenses and year-end tax reporting, including your 1099. Owners get the income without the 2 a.m. phone calls. We manage homes across Maryland, DC and Northern Virginia.
One tax caution before you decide
If you've lived in your home for at least 2 of the last 5 years, you can usually sell it without paying tax on up to $250,000 of gain, or $500,000 for married couples. Rent it out for more than 3 years, and you can lose that break. Rental depreciation can also bring its own tax bill when you sell.
Every situation is different, so talk with your tax advisor before you decide.
Is renting right for you?
The only way to know is to run both sides: what you'd walk away with if you sold today, and what you'd earn if you rented. Our team can do both, since we sell homes, finance them and manage rentals.
If you're weighing your options, call or text my office at 240-255-9027. Give me 15 minutes and I'll show you both numbers side by side.
Or start with a free rental property evaluation. We'll look at what your home would rent for, the local comps, and what it would take to get it rent-ready. No cost, no contract, no pressure: theheywardhomesteam.com/property-management
Sources: Bright MLS September 2026 Housing Market Report; ICE Mortgage Monitor, August 2026; Realtor.com analysis of FHFA data, October 2026; ATTOM, Q2 2026. This post is general information, not tax or legal advice.
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "